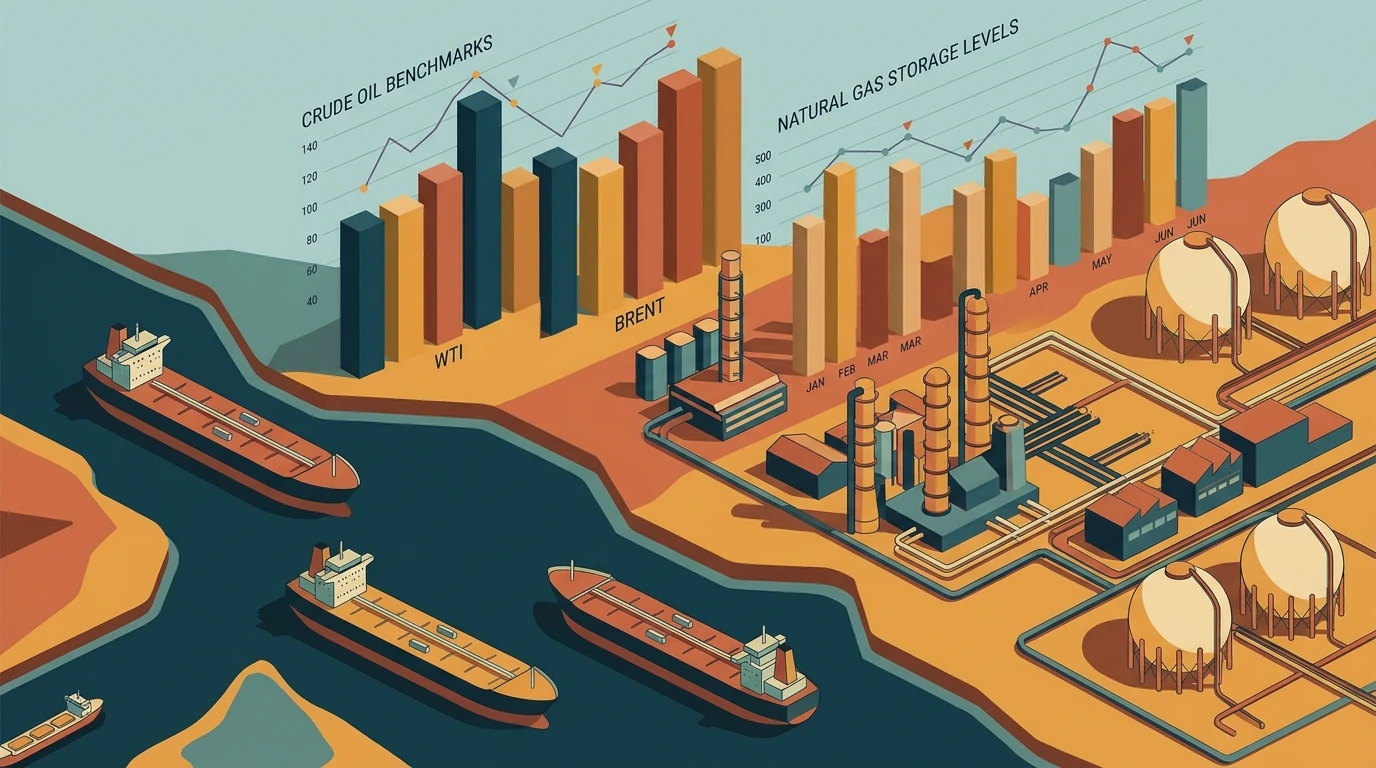
International energy markets entered November 2026 navigating a stark structural divergence. While global crude oil benchmarks hovered near six-month highs above $100 per barrel driven by persistent maritime transit risks in the Persian Gulf, the United States domestic natural gas sector is heading into the winter heating season fortified by robust domestic production and record storage reserves exceeding 3.7 trillion cubic feet (Tcf).
Middle East Geopolitical Premiums and Strait of Hormuz Flow Constraints
Brent crude spot prices consolidated near $104.80 per barrel on the Intercontinental Exchange, while West Texas Intermediate (WTI) held firm around $101.40. Energy analysts attribute the stubborn risk premium to ongoing security friction surrounding the Strait of Hormuz—the maritime chokepoint through which approximately one-fifth of global petroleum consumption and vital liquefied natural gas (LNG) cargoes transit.
In its latest Short-Term Energy Outlook, the U.S. Energy Information Administration (EIA) revised its fourth-quarter global benchmark projections upward, citing elevated maritime insurance surcharges, tanker convoy routing constraints, and intermittent military alerts. While regional producers have partially compensated by redirecting crude through overland bypass pipelines to Red Sea terminals, total transit through Hormuz remains constrained compared to historical operational averages, leaving global supply balances vulnerable to sudden disruption.
US Natural Gas Storage Delivers Record Winter Insulation Buffer
In contrast to the volatile global crude market, the domestic United States natural gas landscape presents a picture of exceptional supply stability. Working gas in underground storage facilities topped 3.74 trillion cubic feet entering November, positioning national inventories well above the five-year seasonal average. Dry shale gas production across the Marcellus, Haynesville, and Permian basins averaged over 112 billion cubic feet per day (Bcf/d), maintaining ample physical availability.
Henry Hub prompt-month futures traded sluggishly in the $2.65 to $2.85 per million British thermal units (MMBtu) range. Mild late-autumn weather patterns across the Midwest and Northeast have suppressed residential and commercial space heating demand, allowing regional utilities to continue net storage injections later into the calendar year than customary.
LNG Export Infrastructure Bridges Domestic Abundance and Global Demand
The stark spread between affordable domestic Henry Hub gas and expensive international spot benchmarks—such as the European Title Transfer Facility (TTF) and Asian Japan Korea Marker (JKM)—has driven American liquefied natural gas export terminals to run near maximum capacity. U.S. LNG export volumes consistently cleared 18.5 Bcf/d throughout October, providing essential baseload energy security to European and Asian utilities facing reduced pipeline deliveries.
Energy market strategists note that while domestic natural gas consumers enjoy significant insulation from overseas price shocks, commercial freight and diesel refining margins remain tightly tethered to global crude valuations. The Department of Energy reaffirmed its readiness to deploy regional fuel reserves if severe winter cold snaps coincide with continued maritime shipping delays.
Editorial Fact Check & Key Findings
Key points
- Brent crude spot price averaged $104.80/bbl on Hormuz transit concerns.
- US underground natural gas storage exceeded 3.74 Tcf entering November.
- US LNG export volumes sustained rates above 18.5 Bcf/d.
What the evidence shows
Brent crude traded above $104 per barrel due to Hormuz maritime risk premiums, while US natural gas inventories surpassed 3.74 Tcf heading into winter.
Background and limits
U.S. LNG export capacity operated above 18.5 Bcf/d, supplying European and Asian utilities while domestic Henry Hub futures stayed under $2.90.
Why this matters
Verifiable commodity inventory levels and maritime shipping metrics inform broader inflationary expectations and household utility costs.