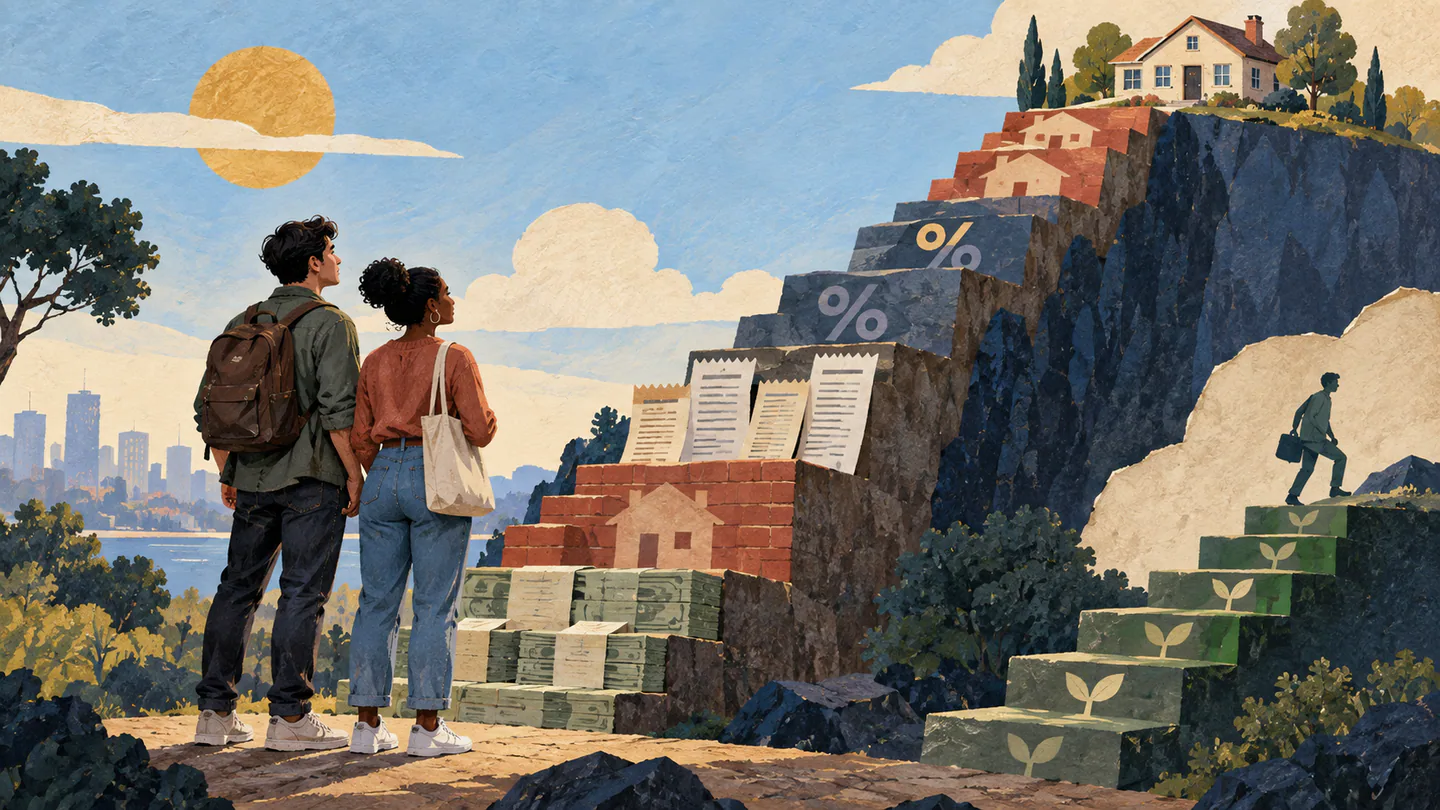
The dream of homeownership has reached an acute crisis point for the Millennial generation, as the median existing-home sales price in the United States reached an all-time record high of $398,000, according to alarming data released by the National Association of Realtors (NAR) and the Federal Reserve Bank of St. Louis. Compounded by sustained mortgage interest rates hovering near seven percent, the typical monthly payment required to service a starter home has more than doubled over the past five years.
The punishing affordability barrier has left millions of middle-class workers in their thirties and early forties—the prime household formation years—locked out of the property market entirely. The homeownership rate among Millennials currently trails previous generations at the same life stage by more than 14 percentage points, forcing young families to delay starting families, postpone retirement savings, or remain indefinitely trapped in hyper-competitive rental markets.
The Paralysis of Inventory and the Golden Handcuff Phenomenon
Housing economists attribute the current crisis to a severe, compounding supply shortage rooted in over a decade of post-2008 underbuilding. The inventory deficit is exacerbated by the pervasive 'golden handcuff' phenomenon, where current homeowners who locked in ultra-low two-to-three percent mortgage rates during the pandemic refuse to list their properties for sale, severely choking off the supply of existing entry-level homes.
Simultaneously, institutional private equity funds and corporate build-to-rent developers have purchased vast tracts of suburban single-family homes, often outbidding individual first-time buyers with aggressive all-cash offers and waived inspection contingencies. This corporate consolidation has further diminished the pool of affordable starter housing in high-growth metropolitan areas.
Bipartisan Policy Proposals and Zoning Reform Debates
The intensifying housing squeeze has emerged as a dominant domestic policy issue on Capitol Hill and in state legislatures across the country. Lawmakers are proposing bipartisan legislation that combines direct federal down-payment assistance grants for first-time buyers with tax incentives to encourage institutional investors to sell single-family housing stock back to individual owner-occupants.
Urban planning reformers are simultaneously challenging restrictive single-family municipal zoning laws, advocating for the legalization of accessory dwelling units (ADUs), duplexes, and transit-oriented townhome communities. Without systemic structural reforms to dramatically expand housing construction, economists warn that the widening wealth gap between property owners and renters could permanently undermine social mobility and middle-class stability.
Editorial Fact Check & Key Findings
Key points
- June median existing-home price: $440,600.
- Annualized sales pace: 4.09 million.
- First-time buying remained near record lows.
What the evidence shows
The median price of an existing US home rose to $440,600 in June, while sales ran at a 4.09 million annual pace. First-time buyers remained a historically small share of purchases.
Background and limits
Affordability depends on mortgage rates, income, insurance, taxes and local supply as well as the sale price. Millennials are not a single market: older and younger members have different incomes, savings and homeownership rates.
Why this matters
A useful affordability story connects price and financing costs to household income instead of declaring a generation to be in “crisis” without a defined benchmark.